Can’t Work After a Truck Accident in Paradise? How Long-Term Income Loss Is Calculated
Many people hurt in a truck crash expect to heal and go back to work, and some never do. Maybe you drove a delivery route, worked shifts near the Strip, or ran your own business, and now a back injury keeps you home. Bills keep coming, and an adjuster may offer a number that covers only your last few paychecks. Before you accept anything, learn how long-term income loss gets measured, whether you run the numbers yourself or ask an experienced Paradise truck accident attorney to check them before you sign.
Lost Wages and Lost Earning Capacity Explained
Income loss after a truck crash falls into two parts. Lost wages cover the pay you have already missed, from the crash date until your claim settles or goes to trial. Lost earning capacity covers the pay you will probably miss later because your injuries limit the work you can do.
Past losses are the easier part, because specific damages like lost wages come straight from pay records. If you earned $28 an hour, worked 40 hours a week, and missed 20 weeks, your lost wages come to $22,400. Overtime, bonuses, and tips count too when your records back them up.
How Future Income Loss Is Estimated
A claim for future income loss compares two numbers. The first is what you could have earned if the crash had never happened, and the second is what you can still earn with your injuries, so the gap between them is your loss. Your age, skills, work history, and health before the crash all help set the first number.
- Past earnings – your average yearly pay before the crash
- Work years left – how many more years you likely would have worked
- Raises – expected pay growth in your trade or field
- Present value – reducing future pay to its worth in today’s dollars
Why Truck Cases Often Carry Larger Income Claims
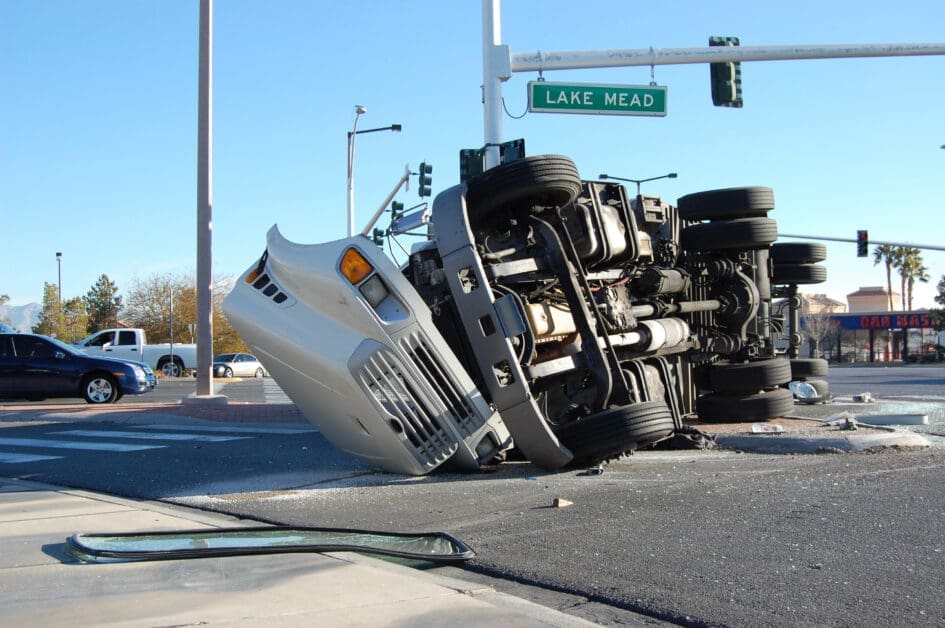
A crash with a loaded truck can cause injuries that end physical work for good, even for people who held the same job for years. Spine, brain, and leg injuries often stretch income loss across decades, which pushes claim values up. Federal rules set a floor for the money behind these claims, since 49 CFR § 387.9 requires a for-hire carrier hauling ordinary freight across state lines in a truck rated at 10,001 pounds or more to carry at least $750,000 in liability coverage.
A carrier can hold more than that minimum, and both the driver and the trucking company may owe damages. Those added sources matter when a long-term income claim grows large. Ask early who owned the truck and who employed the driver, because those answers decide which policies you can claim against.
How Fault and Deadlines Change the Final Number
A strong income claim can still shrink if the other side blames you for part of the crash. Under NRS 41.141, a jury lowers your award by your share of fault, and you can’t recover if your fault is greater than the other side’s. If a jury values your future income loss at $500,000 and puts 10% of the blame on you, you would receive $450,000.
Time limits matter too. Under NRS 11.190(4)(e), most injury lawsuits in Nevada must be filed within two years, and a court can dismiss a late case. Future income loss gets decided in that same lawsuit, so a missed deadline can wipe out the whole claim. Start early, since doctors often need months to learn how permanent your injuries are.
Records That Prove Your Income Loss
Insurers rarely pay for future losses on your word alone. They want records that show what you earned before the crash and what you can earn now. A doctor’s opinion on your work limits often becomes the key document, because it ties your injury to your job.
- Pay records – tax returns, W-2s, and pay stubs from the last few years
- Doctor notes – written work limits, lifting limits, and expected recovery time
- Job details – your duties, work schedule, and any planned promotions
- Business books – profit and loss reports, invoices, and bank deposits if you work for yourself
What a Fair Income Number Really Rests On
A long-term income claim is a forecast, and a forecast gets stronger when facts support each part of it. You can’t prove the future with a single pay stub, so insurers often settle on the smallest number your records allow. Gather your work history and your doctors’ notes early, and have a Nevada attorney test any offer against them before you sign. Small gaps in the record, like a missing tax return or an unsigned work note, give insurers room to cut the number.